A Female Financial Advisor Serving Waukesha and Southeastern Wisconsin
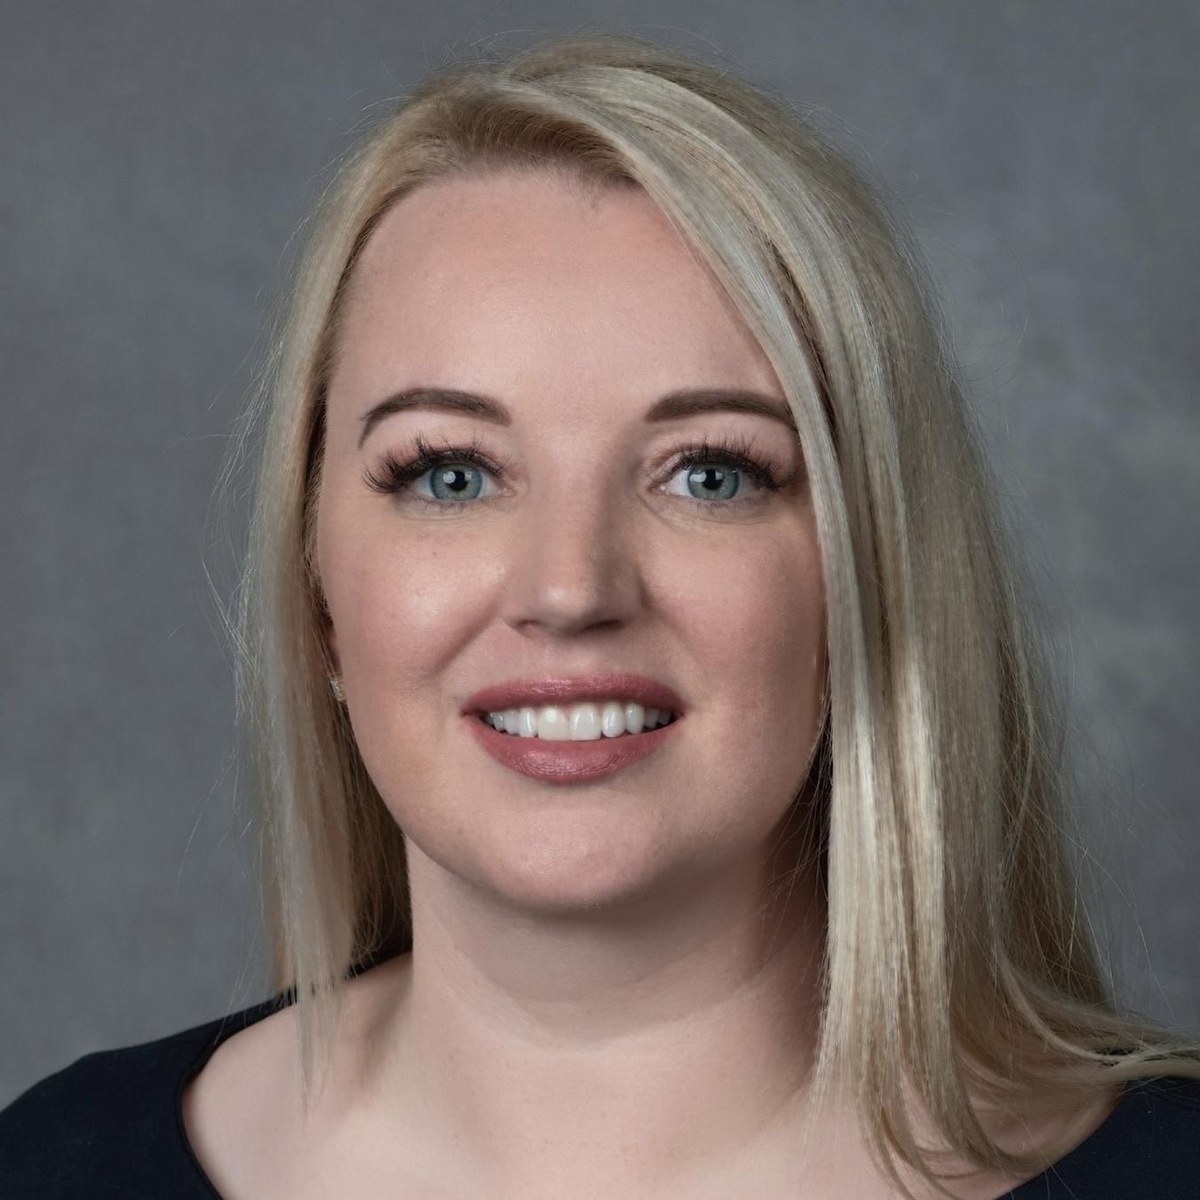
Sarah Elizabeth DePover, MBA, is a female financial advisor with Northwestern Mutual, based in Waukesha. Long-term care planning is her primary practice focus, coordinated with the protection, retirement, and business planning around it.
- Long-Term Care Planning
- Life Insurance & Protection
- Disability Income Insurance
- Retirement & Financial Planning
The short version.
- Advisor
- Sarah Elizabeth DePover, MBA — a female financial advisor
- Affiliation
- Northwestern Mutual
- Primary focus
- Long-term care planning
- Office
- N14W23833 Stone Ridge Dr, Ste 400, Waukesha, WI 53188
- Serves
- Waukesha, Milwaukee metro, southeastern Wisconsin
- Meetings
- In person in Waukesha or by video
A preference worth taking seriously — and never a requirement.
People search for a female financial advisor for practical reasons, not abstract ones. A widow reorganizing accounts after a loss, a woman who has become the primary earner, a couple where one partner has always handled the money and the other wants to understand it, an adult daughter coordinating care decisions for a parent — in each case, the comfort of the conversation shapes how honest it can be.
Sarah's practice reflects that. Conversations start with questions rather than products, move at your pace, and stay in plain language. Nothing about that approach is limited to women: Sarah works with individuals, couples, families, and business owners of any gender. Being a female advisor is simply one reason some households reach out first.
What matters more than preference is fit. A first conversation is meant to establish whether the way Sarah plans matches the way you want to make decisions.
- Questions before recommendations
- Plain language, not product jargon
- Both partners included, not just the one who usually handles money
- Trade-offs explained, including the option to do nothing yet
- Process and compensation explained before any decision
The households and owners she works with most.
Families planning ahead for care
Households who want the long-term care conversation handled early, while options are still open and no one is deciding under pressure.
Women building and protecting wealth
Women navigating career growth, business ownership, inheritance, divorce, or widowhood, who want a plan they fully understand.
Couples and dual-income professionals
Two incomes, two benefits packages, and several accounts that have never been reviewed side by side.
Business owners
Owners coordinating personal protection and retirement with the business that funds the household.
Adult children of aging parents
People trying to understand what care would cost, who would provide it, and what the family should decide before it is urgent.
People with an old 401(k)
Anyone who has changed jobs and left a retirement account behind without reviewing the options.
Long-term care planning is the center of Sarah's practice.
A long-term care advisor helps a family evaluate how extended care would actually be handled — who would provide it, where it would happen, what it could cost, what existing coverage would and would not do, and how paying for it would affect the rest of the plan.
Questions Sarah works through with clients
- Who would provide care, where, and for how long?
- What would care be funded from — income, savings, home equity, or coverage?
- What do Medicare and health insurance generally cover, and what do they not?
- How would an extended care event affect a surviving spouse's income?
- What would change if care were needed at 62 rather than at 82?
- Who in the family needs to know the plan before it is needed?
Medicare is generally designed around medical and short-term skilled care rather than extended custodial care, so families often assume more is covered than actually is. Reviewing that gap early is usually the most useful step. Coverage terms, eligibility, underwriting, and costs vary by person, and nothing here is a recommendation or an offer of coverage.
- Life insurance planning — what a surviving spouse or family would rely on.
- Disability income insurance — what happens to earned income during working years.
- Retirement planning — income timing, withdrawals, and sequencing.
- Old 401(k) and rollover reviews — accounts left behind after a job change.
- Business owner and employee benefits planning — where the business and household plans meet.
What actually happens when you reach out.
- 01
Schedule
Pick a time on Sarah's official Northwestern Mutual calendar, which shows the available appointment types and their durations, or call the office directly.
- 02
Talk
A conversation about your situation, your household, and what is prompting the question now.
- 03
Review
Sarah maps what exists today — coverage, accounts, benefits — and where the gaps sit.
- 04
Decide
You choose whether to keep going. Sarah will explain the process and how she is compensated before any decision.
Waukesha, Milwaukee, and Wisconsin.
Sarah's office is in Waukesha, and much of her practice sits in Waukesha County and the greater Milwaukee metro. She also works with clients across southeastern Wisconsin and elsewhere in the state, meeting by video when that is simpler than driving.
Local pages: Financial advisor in Waukesha, WI · Financial advisor serving Milwaukee, WI · Women & wealth planning
Waukesha, WI 53188